Gold above $4,000: what it means for derivatives regulation
Gold holds above $4,000 as traders wait on the Fed decision and PCE data. What a pause at that level means for hedgers, risk managers and derivatives regulation.
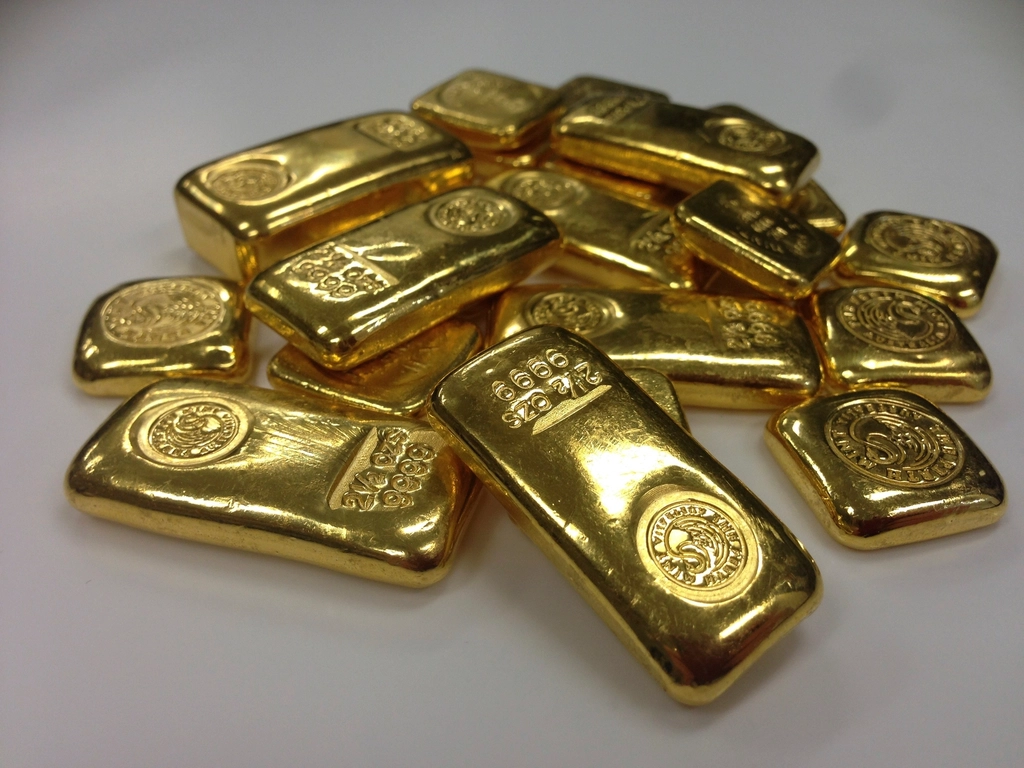
Gold has steadied above $4,000 an ounce as traders wait for a Federal Reserve decision and fresh PCE inflation data, according to Investing.com. The report is short on detail, but the setup is a familiar one. A market that has climbed to a historically high level stops moving while two major macroeconomic events approach. For anyone who watches commodity derivatives through a risk and regulatory lens, a pause like this is often more revealing than a breakout.
Key takeaways
- Gold is holding above the $4,000 mark while the market waits for the Fed’s decision and PCE inflation data, per Investing.com.
- A price pause ahead of scheduled events is when hedgers and risk managers tend to review margin, exposure and liquidity assumptions.
- The futures and options that express views on gold trade in a regulated framework overseen in the US by the CFTC, which makes derivatives regulation relevant even on quiet days.
- What to watch next: the Fed’s decision, the PCE reading, and how gold reacts once both are known.
A round number and a waiting room
Round numbers matter in markets less because of any fundamental significance than because of how people behave around them. A level such as $4,000 becomes a reference point for traders, for risk reports, and for the stress scenarios that institutions run. When gold holds above it rather than racing away, the market is telling us something about conviction: participants are reluctant to add or remove large amounts of risk until the next piece of information arrives.
The two pieces of information in question are well chosen. A Fed decision sets the tone for the cost of money, and gold, which pays no interest, is conventionally read against that backdrop. The PCE data is an inflation gauge closely followed by the central bank. Together they bear on how the market thinks about real rates and the dollar, two of the variables that commonly frame discussion of gold. Investing.com does not, in the report cited here, give a detailed breakdown of expectations, and it would be unwise to read more into the pause than the pause itself.
What can be said is that this is a moment when positioning matters. Traders who are waiting tend to keep position sizes manageable, widen their assumptions about potential moves and, if they are hedgers, think carefully about whether their protection is the right size for the event risk in front of them.
Why a quiet gold market still belongs in a regulation conversation
Gold is both a physical asset and a derivatives market. Much of the price discovery that financial media report on happens in futures and options, which in the United States fall under the oversight of the Commodity Futures Trading Commission. That oversight covers the exchanges and clearinghouses where contracts trade and settle, the intermediaries that carry customer positions, and the rules against manipulation and fraud that apply to everyone.
For a reflective reader, the useful point is that regulation rarely shows itself in a pause. It shows itself in the plumbing that makes the pause safe. Clearinghouses collect margin so that a sharp move after a Fed announcement does not leave a hole in the system. Reporting regimes give supervisors a view of who holds large positions. Enforcement authority exists for the rare cases in which someone tries to distort a market around exactly this sort of scheduled event. None of this is unusual or newly announced; it is the standing architecture that allows a market to digest a high-stakes data release without the participants fearing for their counterparties.
That architecture is also why a price level like $4,000 has consequences beyond the headline. Margin requirements are expressed in dollars per contract, and the dollar value of a gold contract rises with the price. A market at a high price level therefore asks more of its participants in absolute terms, even if the percentage volatility is unchanged. Risk managers know this, and treasury teams at firms that use gold derivatives will often revisit liquidity buffers when the underlying has moved a long way.
Hedgers, speculators and the logic of waiting
It helps to separate the two broad groups in a market like this. Commercial hedgers, such as producers, refiners, jewelers and others with real exposure to the metal, use derivatives to fix a price or limit a range. Their hedging strategy is typically built around business needs rather than a view on the next data release, though the timing of adjustments can be influenced by event risk. Speculative participants, by contrast, take positions because they hold a view about direction or volatility, and they are the ones most likely to trim or hold off ahead of the Fed and PCE.
The distinction matters because the two groups respond differently to the same news and carry different risks. A hedger who is wrong about the market still has the offsetting physical exposure. A speculator does not. Rules on position reporting and limits, together with margin, are designed with that asymmetry in mind: they are meant to keep leverage visible and to make sure losses are absorbed by those who take the risk.
When a market is waiting, those protections are in the background. When the data lands, they become the thing everyone depends on. A reading that surprises in either direction can trigger rapid repricing, and the quality of risk controls is tested within minutes rather than weeks.
What to watch next
The immediate questions are simple. What does the Fed decide, and how does it describe its outlook? Does the PCE reading reinforce or challenge the market’s assumptions about inflation? And does gold hold above $4,000 once those answers are in?
Beyond the next session, a few longer-running questions are worth keeping in view for readers who follow derivatives regulation and risk. One is whether sustained high prices change how participants think about margin and liquidity planning. Another is whether volatility around macro events draws closer attention from supervisors and exchanges. A third is whether hedgers adjust the structure of their protection, for example by relying more on options than on outright futures when event risk is high. None of these has a predetermined answer, and the Investing.com report does not claim one.
For now, the story is one of suspension rather than direction: a metal sitting above a symbolic threshold, a market that has agreed to wait, and a regulatory and clearing framework whose real job is to make sure the waiting ends in an orderly way, whatever the data say. That is not a forecast. It is a reminder that the quiet stretches before big announcements are where the resilience of a derivatives market is quietly built, and where it is later judged.
Prepared with AI assistance from public sources and reviewed under our editorial policy. Not investment advice.